Market Research, Market Size, Market Research Report, Market Share, Market Analysis, Market Growth,

Showing posts with label Medical Devices. Show all posts

Wednesday, March 16, 2022

Medical Supplies Market | Business Overview, Products and Services, Key Insights, Recent Developments

According to the new market research report “Medical Supplies Market by Type (Diagnostic, Dialysis, Wound Care, Disinfectants, PPE, Radiology, Sterilization, Catheters), Application (Urology, Cardiology, Infection Control), End User (Hospitals, Clinics & Physician Offices) – Global Forecast to 2025″, published by MarketsandMarkets™, is projected to reach USD 133.5 billion by 2025 from USD 132.6 billion in 2020.

Recent Developments:

- In 2020, Baxter launched peri-strips dry with secure grip technology for reliable staple line reinforcement in surgical procedures.

- In 2020, Fresenius Medical Care AG & Co. KGaA inaugurated a EUR 30 million expansion of its transfusion and apheresis disposables plant in the Dominican Republic. The new space includes advanced production equipment, plasma kit assembly lines, and sterilization units that double the cleanroom and storage capacity. The site also includes a large warehouse.

- In 2019, Boston Scientific Corporation acquired BTG plc with a focus on offering best-in-class technologies, unparalleled clinical evidence, and strengthened commercial infrastructure.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=64344238

Medical Supplies Market

The increasing prevalence of chronic diseases across the globe, increasing government and corporate investments in healthcare projects and infrastructure development, rising demand for infection control measures to curb the occurrence of HAIs, and the rising demand for medical devices are driving the growth of the global medical supplies market. Moreover, the rising medical tourism and emerging markets are expected to offer significant growth opportunities to players operating in the market for coming years.

Catheters accounted for the largest share of the medical supplies market, by type, in 2019

By type, segmented into diagnostic supplies, infusion & injectable supplies, intubation & ventilation supplies, disinfectants, personal protective equipment, sterilization consumables, wound care consumables, dialysis consumables, radiology consumables, catheters, sleep apnea consumables, and other medical supplies. The intubation & ventilation supplies segment is expected to grow at the highest growth rate during the forecast period. The growth of this segment is driven mainly by the rising prevalence of respiratory diseases such as asthma and COPD across the globe.

By application, the other applications segment accounted for the largest market share in 2019

The applications market is categorized into urology, wound care, radiology, respiratory, infection control, cardiology, IVD, and other applications. The other applications segment held the largest market share in 2019, due to factors such as the increasing number of surgical procedures, rising prevalence of dental diseases, and the increasing focus on adhering to proper waste disposal methods.

Hospitals accounted for the largest share of the medical supplies market, by end user, in 2019

The end-user segment of this market is categorized into hospitals, clinics/physician offices, and other end users. Hospitals form the largest and the fastest-growing end-user segment in the medical supply market. This can be attributed to the increasing investments in healthcare systems and the high prevalence of infectious and chronic diseases.

Request Research Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=64344238

North America was the largest regional market for medical supplies in 2019

The global medical supplies market is segmented into North America, Europe, the Asia Pacific, and the Rest of the World. In 2019, North America accounted for the largest market share, followed by Europe. The increasing incidence of COVID-19 in the US and the implementation of various supportive initiatives by the Canadian Government are the major factors driving the growth of the market in North America.

The prominent players operating in the global medical supplies market include Medtronic (Ireland), Cardinal Health, Inc. (US), BD (US), Johnson & Johnson (US), B. Braun Melsungen AG (Germany), Boston Scientific Corporation (US), Thermo Fisher Scientific, Inc. (US), Baxter International, Inc. (US), Avanos Medical, Inc. (US), 3M (US), Smith & Nephew (Ireland), ConvaTec Group Plc. (UK), Abbott (US), Cook Medical (US), Merit Medical Systems (US), Stryker (US), Terumo Corporation (Japan), Teleflex Incorporated (US), Fresenius Medical Care AG & Co. KGaA (Germany), and Coloplast Group (Denmark).

Speak to Analyst: https://www.marketsandmarkets.com/speaktoanalystNew.asp?id=64344238

Tuesday, March 8, 2022

Fiducial Markers Market - Growth by Top Key Players, Segmentation and Forecast Analysis

The Research Report on “Fiducial Markers Market by Product (Metal Based Markers (Gold, Gold Combination) Polymer Markers), Cancer Type (Prostate, Lung, Breast), Modality (CT, CBCT, MRI, Ultrasound), End user (Hospitals, Outpatient Facilities) – Global Forecast to 2025″, is projected to reach USD 123 million by 2025 from USD 95 million in 2019, at a CAGR of 4.5% from 2019 to 2025.

Recent Developments:

  • In 2019, Stratpharma AG (Switzerland) expanded its agreement with CIVCO (US) to distribute CIVCO’s radiotherapy solutions globally
  • In 2019, IZI Medical Products (US) acquired the RadioMed division of IBA (Belgium), which manufactures the VISICOIL implantable fiducial markers
  • In 2018, Nanovi A/S (Denmark) secured USD 2.23 million from existing investors to expand its business and introduce BioXmark in the European market

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=180673710

Fiducial Markers Market


Industry Segmentation In Detailed:

The metal-based FMs product segment to register significant growth over the forecast period

Based on product, the fiducial markers market is classified into metal-based markers, polymer-based markers, and others. The metal-based markers segment is expected to register significant growth over the forecast period of 2019 to 2025. The adoption of radiotherapy has increased in recent years due to its advantages, such as high precision & radiation control, reduced risk of side-effects, and minimal exposure of healthy tissues to radiation. As metal-based FMs are widely preferred for tumor localization, the rising adoption of radiotherapy procedures is expected to support market growth.

The CT/CBCT modality segment is projected to hold the largest share of the market during the forecast period of 2019 to 2025

On the basis of modality, the fiducial markers market is classified into CT/CBCT, MRI, ultrasound, and radiotherapy. CBCT is preferred for prostate and lung cancer indications, as it effectively detects changes in the position of cancer tumors. Thus, the rising incidences of prostate & lung cancer and the widespread use of CBCT in most developed countries for cancer diagnosis and treatment are the key factors driving the segment growth.

Prostate cancer segment to grow at the highest CAGR over the forecast period

Based on cancer type, the fiducial markers market is broadly segmented into prostate cancer, lung cancer, breast cancer, gastric cancer, and others. Among these, the prostate cancer segment is anticipated to register significant growth over the forecast period due to the rising incidences of prostate cancer globally and the high cure rate associated with radiotherapy. For instance, according to a study published in the Journal of Medical Imaging and Radiation Oncology, the use of EBRT in men suffering from prostate cancer showed a cure rate of ~95.5% for intermediate-risk prostate cancer.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=180673710

Leading Key Players and Analysis:

The major players in the market include CIVCO Radiotherapy (US), IZI Medical Products (US), Boston Scientific Corporation (US), Naslund Medical AB (Sweden), and IBA (Belgium). Other players are Best Medical International, Inc. (US), Nanovi A/S (Denmark), Carbon Medical Technologies (US), Eckert & Ziegler (Germany), Innovative Oncology Solutions (US), Medtronic (Ireland), and QFIX (US).

CIVCO Radiotherapy (US) dominated t­he global fiducial markers market in 2019. Its strong product portfolio and high geographic penetration are the ­key factors contributing to the leading position of this company in the market. In order to maintain its dominant position, the company develops both metal-based as well as polymer-based fiducial markers, such as FusionCoil, PolyMark, FlexiCoil, Align, and PointCoil. The company is also focusing on increasing its presence in developing countries to leverage high-growth opportunities.

Boston Scientific (US) held the second-largest market position in the global judicial markers industry. It became a key player in the market after the launch of its LumiCoil platinum fiducial marker. The company’s strong R&D capabilities and global manufacturing & distribution network are its major strengths.

Geographical Analysis in Detailed:

The fiducial markers market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America is projected to hold the largest share of the regional market for fiducial markers in 2019. This is attributed to the expansion of the target patient population, favorable reimbursement scenario, greater accessibility to radiotherapy procedures, and the presence of major players in this region.

Speak to Analyst: https://www.marketsandmarkets.com/speaktoanalystNew.asp?id=180673710

Thursday, February 17, 2022

Lancets Market Projected to reach US $1,442 million by 2024 | Key players includes Becton, Dickinson and Company (US), Roche Diagnostics (Switzerland)

The Research Report on “Lancets Market by Type (Safety Lancets (Push button, Pressure Activated, Side Button), Personal Lancets), Application (Glucose Testing, Hemoglobin Testing), End User (Hospital, Clinic, Homecare), Region – Global Forecast to 2024″, the lancing devices market is projected to grow at a CAGR of 12.4% during the forecast period to reach USD 1,442 million by 2024 from USD 804 million in 2019.

The Growth in the lancets market is mainly driven by the growing prevalence of diabetes and the high prevalence of infectious diseases across the globe. In addition, emerging markets such as India and China are expected to offer growth opportunities for players operating in the lancets market during the forecast period. However, the risk of needlestick injuries, the reuse of lancets, and the poor reimbursement scenario in developing countries are restricting the growth of Lancing Devices Market.

Recent Developments;

  • In 2018, HTL-STREFA expanded its storage capacity in Leczyca by almost 50%, with an equivalent of 3,550 m2 additional storage space.
  • In 2018, HTL-STREFA was acquired by Investindustrial. This acquisition helped the companies partner for diabetes management, thus serving an extensive customer base.
  • In 2017, Owen Mumford opened its new facility in Malaysia to strengthen and accelerate the growth of the company in the Asia Pacific region.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=86063487

Lancets Market

Industry Segmentation In Detailed:

Safety Lancet is expected to be the most widely used type of the lancets market

The safety lancets accounted for the largest market share in 2018. This is primarily be attributed to the advantages associated with safety lancets such as their ease of use, the capability to prevent needlestick injuries and cross-contamination, and painlessness of vein puncture. In line with this, According to PharmaJet, in the US, around 600,000 to 800,000 needlestick injuries are reported every year. This is expected to increase the demand of safety lancets.

Glucose testing segment is expected to account for the largest share of the lancets market application

The glucose testing segment accounted for the largest share of the lancets market, by application, in 2018. This is primarily due to the increasing prevalence of diabetes, and the need for its prevention and management. For instance, according to the International Diabetes Federation (IDF), in 2017, there were almost 425 million people suffering from diabetes worldwide, and this figure is expected to increase to 629 million by 2045. The growing prevalence of diabetes has resulted in the increased adoption of lancets to effectively handle the growing patient pool.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=86063487

Leading Key Players and Analysis:

Prominent players in the lancets market are Becton, Dickinson and Company (US), Roche Diagnostics (Switzerland), Ypsomed (Switzerland), B. Braun Melsungen (Germany), Terumo Corporation (Japan), Own Mumford (UK), HTL-STREFA S.A (Poland), ARKRAY (Japan), Sarstedt (Germany), and SteriLance Medical (Suzhou) (China).

Roche Diagnostics (Switzerland) was the leading player in the global lancets market in 2018. The company develops and manufactures equipment and reagents used for research and medical diagnostic applications. It offers lancets to various end users including physicians, hospitals, clinics, academic institutes, and for personal use through its Diabetes Care segment. Roche diagnostics invests a significant amount of its revenue in R&D activities to increase its presence in the market. For instance, in 2016, the company invested USD 1.36 billion in diagnostic research and development, which has been increased to USD 1.76 billion in 2018.

Geographical Analysis in Detailed:

North America dominated the lancets market, followed by Europe. Increasing prevalence of diabetes and favorable reimbursement scenario in the region are the factors propelling the growth of the market in the region.

The Asia Pacific region is projected to register the highest growth rate in the global lancets market during the forecast period. This is primarily attributed to the rapid economic growth, rising awareness about diabetes treatment, rising geriatric population in China and India, and Japan’s growing healthcare industry.

Speak to Analyst: https://www.marketsandmarkets.com/speaktoanalystNew.asp?id=86063487

Monday, December 13, 2021

Worldwide Patient Lateral Transfer Market Size, Opportunities for Revenue Growth, and Future Forecast

MarketsandMarkets Research Report’s View on Revenue Impact?

The patient lateral transfer market is expected to reach USD 446.2 million by 2025 from USD 288.7 million in 2020, at a CAGR of 9.1% during the forecast period of 2020 to 2025.

Factors Responsible for Growth and In-Depth Analysis?

Due to the outbreak of corona virus globally, there is a sudden rise in the demand for patient lateral transfer devices. The growth in this market is majorly driven by the high risk of injuries to caregivers during the manual handling of patients, implementation of regulations to minimize manual patient lifting, and the advantages of lateral transfer devices in overcoming persistent difficulties in handling patients with special conditions. However, the lack of training to caregivers for the efficient operation of patient handling equipment is expected to restrain the growth of this market.

– In April 2020, Handicare divested its Patient Handling Europe business to Direct Healthcare Group (UK).

– In February 2020, Sizewise signed an agreement with LINET (Europe).

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=93948116

Patient Lateral Transfer Market


Leading Key Players and Analysis:

Some of the prominent players in Patient Lateral Transfer Market are Stryker Corporation (US), Hill-Rom Holdings, Inc. (US), Sizewise (US), Arjo (Sweden), Haines Medical Australia (Australia), Handicare (Sweden), Medline Industries, Inc. (US), AliMed (US), and Airpal Inc. (US).

Stryker Corporation held 25%-27% share in the patient lateral transfer market. The company provides a suitable range of products in the air-assisted lateral transfer market such as the Sage Prevalon Air Transfer System (MATS). This system reduces the potential risks for back injury. Stryker Corporation has a substantial geographic presence and has rich experience in the global market, making the company one of the top players in the air assisted lateral transfer market. The company has maintained its position in the air-assisted lateral transfer market by focusing on inorganic growth strategy such as acquisitions. For instance, in 2019, Stryker Corporation (US.) acquired Wright Medical Group N.V. (US), a leading medical device company to advance innovation, improve outcomes and reach more patients.

Geographical Analysis in Detailed?

The patient lateral transfer market is segmented into five major regions, namely, North America, Europe, Asia Pacific, Latina America, and the Middle East and Africa. In 2019, North America accounted for the largest share. The large share of North America can primarily be attributed to the growing number of COVID-19 cases, rising prevalence of musculoskeletal disorders among caregivers, growing geriatric population, and the increasing incidence of chronic and lifestyle diseases. Due to its growing geriatric population segment and environmental conditions have favored the spread of COVID-19 which has severely affected the region and ensured enormous growth in the demand for patient lateral transfer devices. Players in this and adjacent, or even non-related, markets have focused on or collaborated for expanding the products of patient lateral transfer.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=93948116

Industry Segmentation:

Rise in the musculoskeletal injuries to caregivers while man handling patients to drive the demand for patient lateral transfer.

Based on product, segmented into air-assisted lateral transfer mattresses, sliding sheets, and accessories. The air-assisted lateral transfer mattresses segment accounted for the largest market share in 2019. The large share of this segment can be attributed to the advantages of these mattresses in overcoming persistent difficulties while handling patients with special conditions.

The hospitals segment accounted for the largest market share in 2019

Based on end users, segmented into hospitals, ambulatory surgery centers, and other end users. Hospitals accounted for the largest share of the patient lateral transfer market in 2019. This can be attributed to many patient admissions in hospitals, rising prevalence of various chronic conditions, and growing regulatory norms to use safe patient transfer equipment. Ambulatory surgery centres are expected to witness the highest growth during the forecast period, mainly due factors such as the growing number of digitalization in healthcare field such as mhealth and teleradiology.

Speak to Analyst: https://www.marketsandmarkets.com/speaktoanalystNew.asp?id=93948116

Tuesday, July 6, 2021

Embolic Protection Devices Market 2021 - Segments, Trends, Share and Forecast Growth

The Research Report on“Embolic Protection Devices Market by Type (Distal Filter, Distal Occlusion, Proximal Occlusion), Material (Nitinol, Polyurethane), Application (Cardiovascular, Neurovascular, Peripheral), Indication (PCI, SVD, TAVR) – Global Forecast to 2023″ published by MarketsandMarkets™, is projected to reach USD 604.9 Million, at a CAGR of 8.3% during the forecast period.

The growth in this market is mainly attributed to factors such as the rising incidence of cardiovascular and neurovascular diseases, growing funding and investments, launch of technologically advanced embolic protection devices, and the rising demand for minimally invasive procedures.

Research Methodology;

Top-down and bottom-up approaches were used to validate the size of the global market and estimate the size of various other dependent submarkets. Major players in the market were identified through secondary sources; directories; databases such as Hoovers, Bloomberg Businessweek, Factiva, and OneSource, journals and their market revenues were determined through primary and secondary research. Secondary research included the study of the annual and financial reports of top market players, whereas primary research included extensive interviews with the key opinion leaders such as CEOs, directors, and marketing executives. The percentage splits, shares, and breakdowns of the product markets were determined using secondary sources and verified through primary sources. All possible parameters that affect the market covered in this research study have been accounted for, viewed in extensive detail, verified through primary research, and analyzed to get the final quantitative and qualitative data.

Request Research Sample Pages:
https://www.marketsandmarkets.com/requestsampleNew.asp?id=158143803


Embolic Protection Devices Market Segmentation in Detailed:

The neurovascular segment is expected to grow at the highest CAGR during the forecast period

On the basis of application, categorized into cardiovascular, neurovascular, and peripheral vascular diseases. The neurovascular segment is expected to grow at the highest CAGR during the forecast period. The favorable medical reimbursement scenarios for neurovascular procedures in developed countries, increasing awareness about the clinical efficacy of embolic protection devices among neurosurgeons, and the rising adoption of these systems across developing countries (such as China and India) are expected to drive the growth of this application segment during the forecast period.

The percutaneous coronary intervention segment accounted for the largest market share in 2017

On the basis of indication, categorized into percutaneous coronary intervention, transcatheter aortic valve replacement (TAVR), carotid artery diseases, saphenous vein graft disease, and other indications. In 2017, the percutaneous coronary intervention segment accounted for the largest share of the global embolic protection devices market. The large share of this segment can primarily be attributed to the increasing prevalence of CAD and the rising preference for minimally invasive procedures.

Geographical View in-detailed:

North America dominated the embolic protection devices market. The rising geriatric population and prevalence of cardiovascular and neurovascular diseases, increasing adoption of minimally invasive techniques, increasing availability of funding, and the presence of a large number of medical device product manufacturers are driving the growth of the market in North America. However, the APAC is expected to grow at the highest CAGR during the forecast period. The high growth of this segment is attributed to the growing geriatric population, rising prevalence of CVD, increasing number of facilities, and rising healthcare expenditure.

Download PDF Brochure: 
https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=158143803

Global Key Leaders:

The prominent players in the embolic protection devices market are Boston Scientific (US), Medtronic  (Ireland), Abbott (US), Cordis (A Cardinal Health Company) (US), Allium Medical (Israel), Contego Medical (US), W.L. Gore & Associates (US), Silk Road Medical (US), Claret Medical (US), and AngioSlide (Israel).

Monday, June 17, 2019

Veterinary Chemistry Analyzer Market Revenue, Demand, Opportunity, Segment and Key Trends 2019

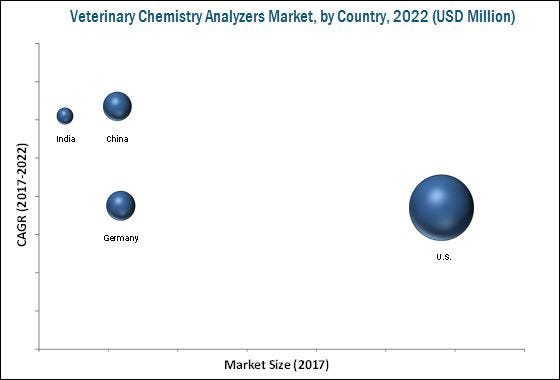
According to the new market research report “Veterinary Chemistry Analyzer Market by Product (Chemistry Analyzer, Glucometer, Consumables (Panel, Test Strip, Reagent)) Application (Blood Chemistry Analysis, Urinalysis, Glucose Monitoring) & Animal (Companion & Livestock) — Global Forecast”,published by MarketsandMarkets™, the Global Veterinary Chemistry Analyzer Market is estimated to grow at a CAGR of 8.7%, to reach USD 1,205.2 Million.
The growth in this market is majorly attributed to factors such as growing livestock and companion animal population, rising animal healthcare expenditure, rising pet adoption, growing demand for animal-derived food products, raising awareness about zoonotic diseases, and an increasing number of veterinary practitioners across the globe.
Read a Press Release on “Veterinary Chemistry Analyzer Market”:
The Global Veterinary Chemistry Analyzer Market is segmented on the basis of product, application, animal type, and region. On the basis of product, this market is segmented into instruments and consumables (panels, kits, test strips, and reagents). In 2016, the consumables segment accounted for the largest share of the global Veterinary Chemistry Analyzer Market. It is expected to register the highest growth during the forecast period. The high growth of this segment is mainly attributed to the increased adoption of the pre-loaded multiple reagent panels and pre-loaded single slide reagent panels by the end users.
Browse and in-depth TOC on “Veterinary Chemistry Analyzer Market”
206 — Tables
24 — Figures
250 — Pages
On the basis of application, the market is categorized into blood chemistry analysis, urinalysis, glucose monitoring, and blood gas-electrolyte analysis. The blood chemistry analysis segment accounted for the largest share, while the glucose-monitoring segment is expected to witness the highest growth during the forecast period. The Veterinary Chemistry Analyzer Market is further segmented, on the basis of animal type, into companion animals and livestock. The companion animal segment accounted for the largest share of the market. This segment is also expected to register the highest growth during the forecast period.
The report also provides a detailed geographic analysis of the Veterinary Chemistry Analyzer Market covering developed and emerging economies. The developed market includes the U.S., Canada, Germany, the U.K., France, Italy, Spain, and Japan while the emerging market includes China, India, and Latin America. The U.S. attributed the largest share of the developed market owing to its well-established animal healthcare systems. The large share of this regional market segment is driven by increasing demand for animal-derived food products, rising animal healthcare expenditure, growing animal population, and raising awareness about zoonotic diseases.
Some of the prominent players in this market are IDEXX Laboratories, Inc. (U.S.), Abaxis, Inc. (U.S.), Heska Corporation (U.S.), Randox Laboratories Ltd. (U.K.), ARKRAY, Inc. (Japan), Eurolyser Diagnostica GmbH (Austria), Alfa Wassermann Inc. (U.S.), DiaSys Diagnostic Systems, USA, LLC (U.S.), Diconex SA (Argentina), Chengdu Seamaty Technology Co., Ltd.(China), Biochemical Systems International Srl (Italy), ELITechGroup (France), and URIT Medical Electronic Group Co. Ltd (China).
Know more about key industry players:

Monday, May 20, 2019

Fractional Flow Reserve Market | Business Overview, Products and Services, Key Insights, Recent Developments

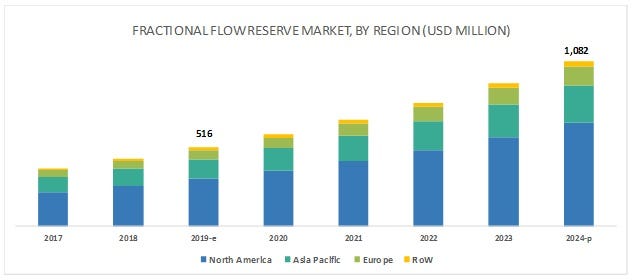
The Fractional Flow Reserve Market growth is largely driven by the increasing geriatric population and the subsequent growth in the prevalence of cardiovascular diseases, cost-benefits of FFR, and the presence of a favorable reimbursement scenario. Emerging economies are expected to present market players with a wide range of opportunities.
The Fractional Flow Reserve Market is projected to reach USD 1,082 million by 2024 from USD 516 million in 2019, at a CAGR of 16.0% during the forecast period.
Download PDF Brochure:
The invasive monitoring segment accounted for the largest share of the market in 2018
On the basis of technology, the market is segmented into invasive and non-invasive monitoring technologies. In 2018, the invasive monitoring segment accounted for the largest share of the Fractional Flow Reserve Market. The large share of this segment can be attributed to the strong recommendation for FFR usage in coronary angiography.
The pressure guidewires segment is expected to grow at the highest CAGR during the forecast period
On the basis of product, the invasive monitoring market is segmented into pressure guidewires and FFR monitoring systems. The pressure guidewires segment accounted for the largest share of the market in 2018. This can be attributed to the growth in the number of PCI procedures (as a result of the rising prevalence of CVD), strong recommendation for the use of guided revascularization by measuring FFR in specific clinical scenarios, and the single-use nature of pressure guidewires, which ensures repeat purchases.
Recent Developments in Fractional Flow Reserve Market:
  • In 2017, Abbott acquired St. Jude Medical, Inc., one of the leading players in cardiovascular and neuromodulation products.
     Abbott Laboratories is a healthcare company that develops, manufactures, and markets a broad and diverse range of health care products. The company operates through four business segments, namely, Established Pharmaceuticals, Diagnostic Products, Nutritional Products, and Cardiovascular and Neuromodulation Products. The company is present in Africa, Asia Pacific, Europe, Latin America, the Middle East, North America, and South America.
  • In 2017, HeartFlow, Inc. entered into an agreement with Royal Philips
     Founded in 2007 and headquartered in California (US), HeartFlow is a personalized medical technology company seeking to transform the way cardiovascular disease is diagnosed and treated. The company provides Heartflow FFR-CT, the first available non-invasive solution that enables a physician to more accurately evaluate whether a patient has significant coronary artery disease (CAD) based on both anatomy and physiology. HeartFlow FFRct leverages deep learning to create a personalized 3D model of the patient’s arteries. Through this agreement, Philips will promote the use of the HeartFlow FFRct Analysis in conjunction with Philips’ advanced catheters for the imaging and assessment of a patient’s coronary arteries.
Read a Press Release on “Fractional Flow Reserve Market”:https://www.marketsandmarkets.com/PressReleases/fractional-flow-reserve.asp
Key Questions addressed by the report:
  • Which are the key players in the market, and how intense is the competition?
  • Emerging countries present immense opportunities for the growth of Fractional Flow Reserve Market. Will this situation persist?
  • Which product markets will dominate in the future?
  • What are the challenges hindering the adoption of fractional flow reserve solutions?

Friday, May 17, 2019

Additive Manufacturing Market 2019: Global Industry Size, Segments, Share and Growth Factor Analysis Research Report

According to the American Society for Testing and Materials (ASTM), “additive manufacturing” is the “process of joining materials to make objects from 3D model data, usually layer upon layer”. Various synonyms generally used for AM are an additive fabrication, additive processes, additive techniques, additive layer manufacturing, layer manufacturing, and freeform fabrication.
The Additive Manufacturing Market is expected to grow at a CAGR of 13.5% to reach $3,471.9 million
Technological innovations in 3d printing have been witnessed over the past few years. Newer surgical products manufactured from AM, with better safety and efficacy attributes, contribute to the widespread adoption of the additive manufacturing in medical by physicians and patients worldwide.
Download PDF (AM Market):
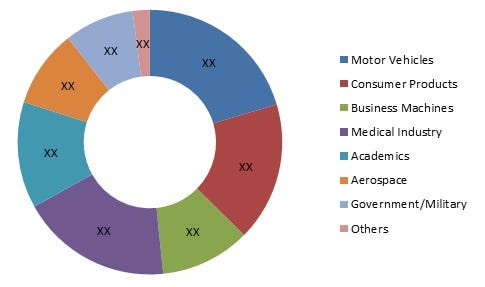
Global 3D Printing Market, by industry
  • Automotives
  • Consumer products
  • Business machines
  • Medical
  • Academic
  • Aerospace
  • Government/military
Automotive or motor vehicles account for the largest share in this market, primarily due to the easy applications of 3D printing in the production of end-products (engines, spare parts, other interior, and exterior parts) as compared to other segments such as consumer products and business machines, which have limited usage in manufacturing of end-products. Rising healthcare expenditure in emerging economies provides growth opportunities for AM technologies, as new healthcare facilities have come up in these areas.
Request Research Sample Pages:
Geographical Analysis of Additive Manufacturing Market:
Europe accounts for the largest market share of the global additive manufacturing for medical devices market, followed by North America. In the future, it is estimated that the share of the European region will decrease, attributable to lowering device prices, regulatory pressures, and increasing focus of players towards emerging markets in the Asian and Latin American regions.
Major Key Players in Additive Manufacturing Market:
The key players in this market are 3D Systems Corporation (U.S.), 3T RPD (U.K.), Arcam AB (Sweden), Biomedical Modeling, Inc. (U.S.), Envisiontec GmbH (Germany), EOS GmbH Electro Optical Systems (Germany), Fcubic AB (Sweden), GPI Prototype and Manufacturing Services, Inc. (U.S.), Greatbatch, Inc. (U.S.), Layerwise NV (Belgium), Limacorporate SPA (Italy), Materialise NV (Belgium), Medical Modeling, Inc. (U.S.), and others.